Is MSTR a cheap way to own bitcoin? mNAV says 0.69x
También disponible en español →
One number decides whether buying Strategy is a cheap way to own bitcoin: the mNAV, what the market pays for the company against what its bitcoin is worth. This week it reads 0.69x, with Bitcoin at $76,206 and MSTR at $126.
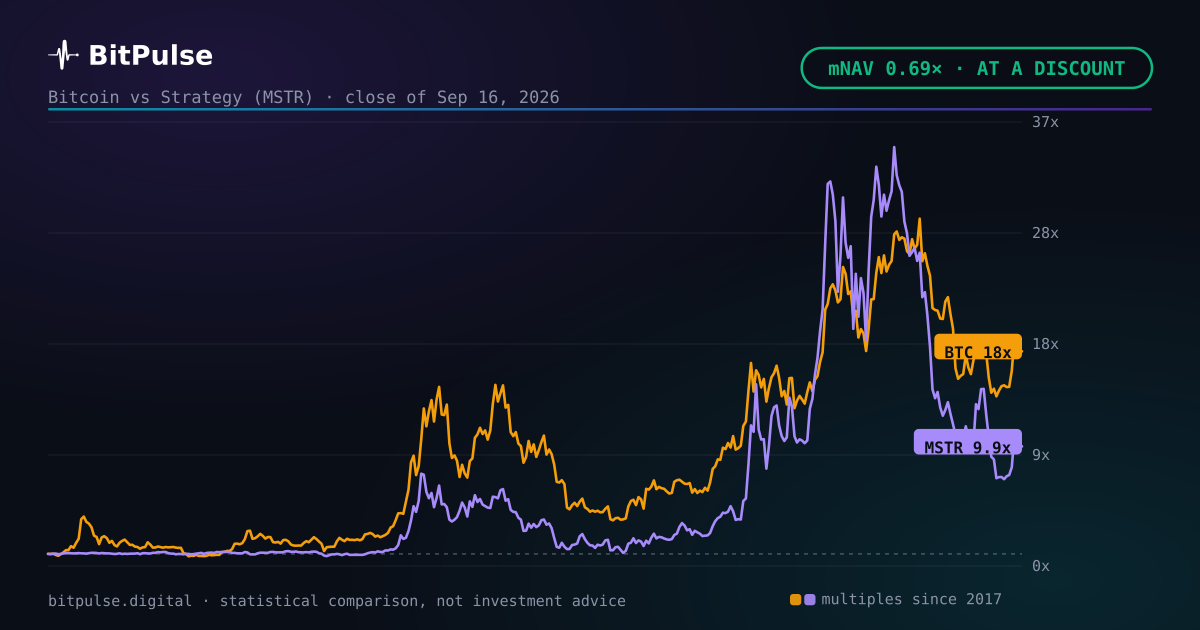
What the market pays for Strategy against its bitcoin
The bitcoin on Strategy's balance sheet is worth 64.4 billion dollars at the latest close. The market prices the entire firm, every share counted, at 44.5 billion dollars. Divide one by the other and you get the mNAV: 0.69x.
Below 1 means the stock trades for less than the bitcoin it owns. Put bluntly, the market is pricing every dollar of bitcoin on that balance sheet at 0.69 dollars. That discount is not free money: it exists because a company is not a wallet, and the sections below are the reasons the market gives for it.
Last week, same series: Strategy (MSTR) holds 845,050 BTC and trades at 71% of them. That range is already settled and published, hit or miss.
The range comes out of a four-model engine, reweighted every week against the real record. How it is calculated, step by step.
The largest bitcoin treasury, and what it cost to build
One layer deeper. 845,050 bitcoin, around 4.02% of every coin that will ever exist. No other listed company is close, and the figure comes from official filings rather than from an estimate.
They paid an average of $76,052 per coin. With Bitcoin at $76,206, that position sits +0.2% from its cost. In profit, in plain words: the company is currently up on the bitcoin it bought. That number moves every day and it is the cleanest way to read the position without a story attached.
The sources, and one honest caveat
Zoom out for a second. Holdings, cost, debt and share count come from Strategy's own filings. Prices come from the daily closes of both assets. Nothing here is an estimate and nothing is rounded to make a point.
One caveat worth stating: the stock market closes and Bitcoin does not. These figures use the close of September 16, 2026, so the stock side is a day behind the coin side by construction. On a quiet week that changes nothing; on a violent one it is worth remembering before comparing the two.
The debt behind the bitcoin, and when it comes due
Long-term debt stands at 6.7 billion dollars, which is 10 dollars owed for every 100 dollars of bitcoin held. Figures as of 2026-06-30, from the filings, so they move once a quarter rather than every day.
The first large maturity is 4.5 billion dollars. Debt is what separates this from simply owning coins: a wallet never has to refinance. It is also why the discount or premium on the mNAV is never just arithmetic.
What the public log says so far
Set the price aside for a moment. 9 of the 11 projected weekly ranges published so far resolved inside the band. Every one of them was frozen before its week, and every result went up afterwards, including the ones that went wrong.
There is a trap in that number worth naming. A band that contains the close every single time is not a good model, it is a wide one. The published band is the middle half of the distribution, so a properly calibrated engine should land inside about half the time. A hit rate far above that means the bands are wider than they should be, which is a miscalibration too, just the flattering kind.
The forecast is for Bitcoin, not for MSTR
The BitPulse engine forecasts Bitcoin, and only Bitcoin. Everything on this page is a statistical comparison between two assets: no target price for the stock, no view on where it goes next, and no intention of adding one.
A company carries risks a currency does not. Debt that has to be refinanced, management decisions, regulation, and a share count that can change. None of this is investment advice, and a discount on the mNAV is a fact about today, not a promise about tomorrow.
Frequently asked questions
What is MSTR mNAV and why does it matter?
It is what the whole company is worth divided by what its bitcoin is worth. Today it reads 0.69x: the stock trades BELOW its reserves, so the market pays less than a dollar for every dollar of bitcoin on its balance sheet. It is the number that decides whether buying the stock is cheaper or dearer than buying the coin.
How is the Bitcoin range calculated?
With a combined engine of four models: a power law over a decade of price history, a Monte Carlo simulation driven by GARCH volatility, an Ornstein-Uhlenbeck residual model and an implied density read from the Deribit options surface. They are pooled into one distribution and reweighted every week against real history, with around fourteen live data sources feeding a bias layer on top. The published band is its middle half, frozen before the period starts so it cannot be adjusted after the fact.
Where is Bitcoin in its market cycle?
Day 881 since the last halving. The model uses that position as one of its signals, alongside recent volatility and the long-term trend.
Published before the fact
Bitcoin dominance: – · Altseason: –
The 7, 30 and 90-day zones are checked on the free account; from six months to three years belongs to Pro. See the plans →